Why your visa, tax residency, overseas salary and employer obligations may follow different rules.
The stamp in your passport is only the beginning
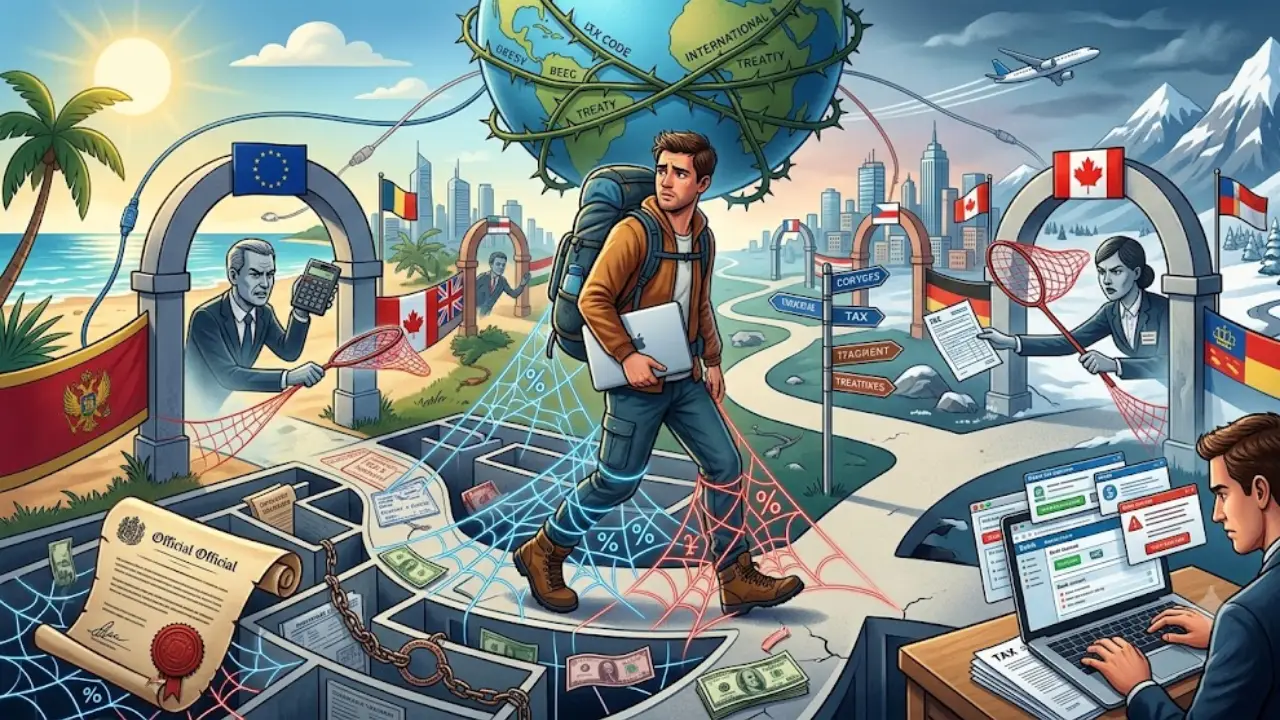
Imagine Maya, a software consultant from India. She spends four months in Portugal, three in Thailand, two in Dubai and the rest of the year visiting family. Her employer remains in India. Her salary arrives in an Indian bank account. She has never overstayed a visa, never missed a client deadline and never considered herself a tax resident anywhere except home.
Then a tax adviser asks a deceptively simple question: Where did you actually work, and where were you legally resident when you earned that income?
Maya has flight tickets, hotel invoices and a digital-nomad visa. What she does not have is a clear answer.
Her problem is not unusual in principle. Remote work has separated three things that once appeared to belong together: where people live, where they work and where they pay tax. Governments, however, have not abandoned their rights to tax income simply because an employee can carry a laptop across a border.
The International Labour Organization, tax authorities and international policy-makers have all had to confront the consequences of increasingly mobile work. In November 2025, the OECD updated its Model Tax Convention with additional guidance on when cross-border home working may create a taxable business presence. Its May 2026 explanation highlights the distinction between personal convenience and a commercially driven presence abroad.
The lesson is clear: a digital-nomad visa is an immigration permission, not a universal tax exemption.
Five concepts that must never be confused
The first mistake is treating several different legal tests as though they were one.
| Concept | What it actually determines | Why it matters |
| Immigration status | Whether you may enter, stay or work under local immigration rules | A visa may restrict employment or clients even when tax is paid |
| Physical presence | The days you are physically in a country | These days may trigger residence tests or other obligations |
| Tax residence | Whether a country’s tax law treats you as resident | Residents may face tax on worldwide income, depending on local law |
| Domicile | A legal concept whose meaning varies by jurisdiction | In some systems, domicile or long-term connections affect tax liability |
| Citizenship | Your legal nationality | Some countries, notably the United States, tax citizens on worldwide income even when living abroad, subject to applicable rules and relief |
Source of income is a sixth, separate question. A salary may be paid by an Indian employer into an Indian bank account while the employee physically performs the work in another country. The payment destination does not, by itself, decide where the income is taxable.
Tax authorities may examine where employment duties were performed, the employer’s location, the nature of the income and the applicable tax treaty.
A country may also tax certain locally sourced income earned by a non-resident. Conversely, a person may become tax-resident without acquiring citizenship or permanent immigration status.
The practical implication is that every move requires separate immigration and tax checks. One approval cannot safely substitute for the other.
The famous 183-day rule is not a universal escape hatch
The number 183 has become a favourite of online relocation advice. It is useful, but frequently misunderstood.
Countries use different residence tests. Some consider days of physical presence; others also examine accommodation, family, economic interests, habitual residence or other statutory connections. Some have special rules for citizens, returning residents or people with substantial local income.
Even the counting method can differ. A country may count a day of arrival or departure, use a calendar year, or apply a different tax-year period.
For example, the United States generally applies a substantial-presence test to many non-citizens using a weighted calculation across three calendar years. It also has a separate green-card test. Citizenship can create continuing US tax obligations even when a citizen lives abroad.
India has its own statutory residence tests. Under section 6 of the Income-tax Act, 2025, the basic individual tests include 182 days in the relevant tax year, or 60 days in that year combined with 365 days in the preceding four years, subject to statutory exceptions and special provisions. Indian citizens leaving for overseas employment and certain visiting citizens or persons of Indian origin may be subject to modified rules.
India’s tax year runs from 1 April to 31 March, unlike the US calendar-year framework.
The correct question is therefore not, “Have I stayed fewer than 183 days?”
It is: “Which residence tests apply to me in every relevant country, and what do they say when considered together?”
A person can potentially be treated as resident under the domestic laws of two countries during the same period. That is when treaty rules become particularly important.
How spending a few months in several countries creates a legal footprint
Return to Maya’s itinerary.
She spends 120 days in Country A, 100 in Country B, 75 in Country C and 70 in India. None of these totals independently reaches 183 days.
That does not prove that she owes no tax anywhere.
The example is illustrative, not a tax calculation. Each country could apply different tests, and Maya’s citizenship, home, family connections, employment arrangements and income sources could change the result.
Her 120 days in Country A might matter under a residence test that does not require 183 days. Her home and personal connections could matter elsewhere. Her employment income might be taxable in a country where she physically carried out her duties, depending on domestic law and treaty provisions.
The problem grows when her employer has clients, offices or business activities in those countries.
This is the fragmentation trap: travel planning may divide a year into neat blocks, while tax law examines the same year through several overlapping legal systems.
Build a defensible travel-day record
Maintain a spreadsheet or secure log with:
Date of entry and departure for every country.
Passport stamps, boarding passes and travel confirmations.
Accommodation records and local registration documents.
Days spent working, on leave or travelling between countries.
The physical location where employment duties were performed.
Contracts, payslips and records of foreign tax withheld.
Record the date and country each time you cross a border. Reconcile the log against travel documents monthly rather than reconstructing the year from memory.
Do not assume that an airport transit, overnight flight or departure date is counted identically everywhere. Confirm the local rule.
Digital-nomad visas: permission to stay is not permission to ignore tax
Digital-nomad visas are designed to facilitate temporary stays for eligible remote workers, freelancers and other qualifying applicants. Their precise conditions differ.
Some programmes require proof of foreign employment or minimum income. Others impose restrictions on local employment, local clients or the type of business activity permitted.
A visa may offer favourable tax treatment under specific conditions, but the existence of a visa alone does not establish an exemption.
Before applying, investigate three distinct questions:
- Immigration: Does the visa permit your particular work arrangement, including your employer and clients?
- Personal taxation: Will you be tax-resident, or otherwise taxable on the income you earn while present?
- Business taxation: Could your activities create registration, payroll, withholding or corporate tax obligations for your employer or business?
Never rely solely on a relocation firm’s headline saying “zero tax” or “tax-free remote work.” Ask which statute or official tax-authority guidance establishes the benefit, who qualifies, which income is covered and whether the relief expires.
The employer’s hidden problem: permanent establishment
An employee may think moving abroad is a personal decision. The employer may see a corporate tax risk.
Under many tax treaties, a foreign business can become taxable on profits attributable to a permanent establishment in another country. The precise definition depends on the applicable treaty and domestic law.
Could an employee’s home office create that risk?
The OECD’s 2025 Model Tax Convention update clarifies the analysis of cross-border home working. Its guidance does not say that every employee working abroad creates a taxable presence. Instead, the circumstances matter.
A useful distinction is between working abroad for personal convenience and being there for a commercial reason connected with the enterprise. The amount of working time in the foreign location and the nature of the employee’s role can also matter.
For example, an employee who works occasionally from a holiday rental presents a different fact pattern from a senior executive who habitually negotiates contracts, manages operations or serves local customers from a foreign home office.
The OECD’s guidance uses working-time examples, including a case where working from the foreign home for less than 50% of the relevant 12-month period, without other significant factors, would generally not by itself make the home a place of business. That is an analytical example, not a universal safe harbour.
Existing bilateral treaties and local laws must be checked. The OECD Model is not itself a treaty automatically binding every country.
Other employer issues can include:
Local payroll registration and wage withholding.
Employer social-security contributions.
Mandatory employment protections.
Corporate reporting and local business registration.
Data protection, confidentiality and regulated-industry requirements.
Before approving an overseas work arrangement, an employer should obtain a country-specific review rather than treating remote work as an informal employee benefit.
Double-taxation agreements: relief, not immunity
A Double Taxation Avoidance Agreement (DTAA) coordinates taxing rights between countries and provides mechanisms for reducing double taxation. It does not necessarily prevent both countries from initially asserting a right to tax.
A treaty may contain provisions addressing:
Residence: How a person who qualifies as resident under both countries’ domestic laws is treated for treaty purposes.
Employment income: Which country may tax salary and when a short-stay exception applies.
Permanent establishment: When business profits may be taxed in another country.
Foreign tax relief: How qualifying taxes paid abroad may be credited or otherwise relieved.
Mutual agreement procedures: How competent authorities can address certain treaty disputes.
For individuals treated as resident in both treaty countries, the applicable agreement may use a sequence of tests involving a permanent home, closer personal and economic relations, habitual abode and, in some treaties, nationality or competent-authority agreement.
The exact wording matters.
Why the 183-day employment exception can fail
Many treaties contain a short-stay exception for employment income. Common conditions include staying within a specified day limit, having remuneration paid by or on behalf of an employer that is not resident in the work country, and ensuring the remuneration is not borne by a permanent establishment there.
All relevant conditions must be met. The counting period and wording depend on the treaty.
Therefore, staying for fewer than 183 days does not automatically make the salary exempt. Nor does a treaty necessarily eliminate filing requirements.
For an Indian taxpayer, the Income Tax Department provides official information on DTAAs and foreign tax credit (FTC). Relief may be available under the relevant agreement and domestic provisions, while unilateral relief may be available in certain cases where no agreement exists.
Keep foreign tax assessments, withholding certificates and proof of payment. The eligibility, limits, documentation and filing procedure must be verified for the relevant tax year.
Freelancers and business owners face a different set of risks
An employee and a self-employed consultant should not assume they face identical rules.
A freelancer may receive fees from clients in several countries. Depending on the legal classification of the income and applicable rules, the analysis may involve business profits, independent professional services, royalties or other categories.
A company founder working abroad may create additional questions about where the business is managed, whether it has a taxable presence, whether local registration is required and how profits are allocated.
Even a one-person business can have administrative obligations. Local VAT or GST-style taxes, invoicing requirements, withholding rules and business licences may apply independently of personal income-tax residence.
Before moving, prepare a list of every income stream: salary, consulting fees, business profits, dividends, interest, rental income, capital gains and royalties. Do not assume they all receive the same treaty treatment.
Social security, employment law and insurance: the overlooked three
Income tax is only one part of the cost of working abroad.
Social security. Depending on the countries involved, you may need to determine where pension, healthcare, unemployment or other contributions are due. Some countries have bilateral social-security agreements; others do not. European Union coordination rules, for example, can determine which member state’s system covers a person working in multiple countries. The outcome depends on the person’s work pattern and circumstances, not simply nationality.
Employment law. Mandatory rules in the country where work is performed may affect working hours, paid leave, minimum employment standards, termination rights and workplace protections. A foreign employment contract does not automatically displace every local rule.
Insurance. Ordinary travel insurance may exclude routine medical treatment, long stays, work-related incidents or pre-existing conditions. Check the policy’s territorial scope, duration, evacuation cover and whether it explicitly permits the intended activity. Verify that health insurance satisfies visa requirements where applicable.
A tax plan that ignores these three areas may be financially incomplete even if its income-tax analysis is correct.
The practical pre-move checklist
Use this sequence before booking a long stay or committing to a relocation.
| Step | What to do | Evidence to keep |
| 1. Visa | Confirm permitted work, client restrictions, stay duration and renewal conditions | Visa approval and official conditions |
| 2. Tax residence | Test residence under the laws of your home and destination countries | Day-count log, residence analysis |
| 3. Income source | Classify each income stream and determine where work is performed | Contracts, invoices, payslips |
| 4. Employer obligations | Ask the employer to assess payroll, withholding and permanent-establishment risk | Written employer approval and tax review |
| 5. Social security | Check contribution rules and any applicable bilateral agreement | Coverage certificate and contribution records |
| 6. Insurance | Confirm cover for the entire stay and intended work | Policy wording and insurer confirmation |
| 7. Treaty | Read the actual bilateral treaty, including residence and income-specific provisions | Treaty text, tax residency certificate where required |
| 8. Reporting | Confirm tax returns, foreign tax credits and local registration deadlines | Filing calendar and payment receipts |
A practical decision rule
If you cannot confidently answer where you may be taxable, whether your employer has approved the arrangement and how you will remain insured, do not treat the move as administratively complete.
Seek written advice before departure when the income is substantial, the stay is lengthy, the employer has no overseas compliance infrastructure, or you own a business. The cost of an advance review is often easier to control than a tax assessment, payroll dispute or missed filing deadline.
What the evidence tells us about the future
Remote work has made a worker’s physical location easier to change, but it has not made the legal consequences disappear.
The OECD’s 2025 update and 2026 explanatory analysis are significant because they address a problem that older office-centred assumptions did not fully anticipate: an employee’s home can be temporary, personal and commercially irrelevant in one situation, yet form part of an enterprise’s operations in another.
The future is unlikely to be governed by one global nomad tax rule. Instead, workers and employers will need to navigate overlapping national laws, bilateral treaties, reporting systems and increasingly detailed records of where work occurs.
This creates a new form of professional responsibility. The mobile worker must understand the consequences of location; the employer must assess the business risk; and tax advisers must consider the full cross-border picture rather than one country’s day-count rule in isolation.
The freedom to work from anywhere is real. The freedom to ignore where “anywhere” happens to be is not.
Make the paperwork part of the journey
Before moving, establish your visa rights, determine tax residence under each relevant country’s law, classify your income, check employer and social-security obligations, verify insurance and read the applicable treaty.
Keep reliable records of travel and workdays. Do not treat 183 days as a universal exemption, a foreign bank account as proof of foreign-source income, or a digital-nomad visa as a tax ruling.
Above all, seek qualified cross-border advice when the stakes are significant. A well-planned relocation should deliver freedom without leaving an expensive legal mystery behind.
Frequently asked questions
1. Does a digital-nomad visa mean I pay no income tax?
No. It grants immigration permission under specific conditions. Tax liability depends on domestic law, the nature and source of income, residence status and any applicable treaty or special tax regime.
2. If I spend fewer than 183 days in every country, am I tax-free?
Not necessarily. Countries use different residence tests, and income may be taxable even when you are not resident. The relevant treaty may also impose conditions beyond a day-count limit.
3. Can two countries consider me tax-resident in the same year?
Yes, potentially. Their domestic laws may overlap. An applicable treaty may resolve dual residence for treaty purposes, but its wording and the facts must be examined.
4. Can my employer face tax consequences because I work abroad?
Potentially. Payroll, withholding, employment-law and permanent-establishment risks depend on the destination country, the employee’s duties, the duration and commercial circumstances.
5. What records should a digital nomad keep?
Maintain a daily country-by-country travel log, travel documents, accommodation records, work-location records, employment contracts, invoices, payslips and foreign tax-payment evidence.
6. Should I consult a tax adviser before moving?
Yes, particularly if you have substantial income, multiple clients, equity compensation, a business, a long stay or possible residence in more than one country. Choose an adviser familiar with both the home and destination jurisdictions.
Sources and official government resources
- OECD — 2025 Model Tax Convention update: Remote work and cross-border business taxation.
- OECD — May 2026 analysis: Home and away: When does working remotely across borders create a taxable presence?.
- Income Tax Department, Government of India: Residential status under section 6.
- Income Tax Department, Government of India: Double Taxation Avoidance Agreements.
- Income Tax Department, Government of India: Double taxation relief and foreign tax credit.
- Internal Revenue Service, United States: Introduction to residency under US tax law.
- European Union — Your Europe: Social security cover when living or working in another EU country.
Disclaimer: This article is educational, not individual legal or tax advice. Immigration rules, domestic tax laws, treaties and administrative requirements change. Confirm current rules with the relevant authorities and a qualified cross-border tax professional before acting.
Leave a Reply