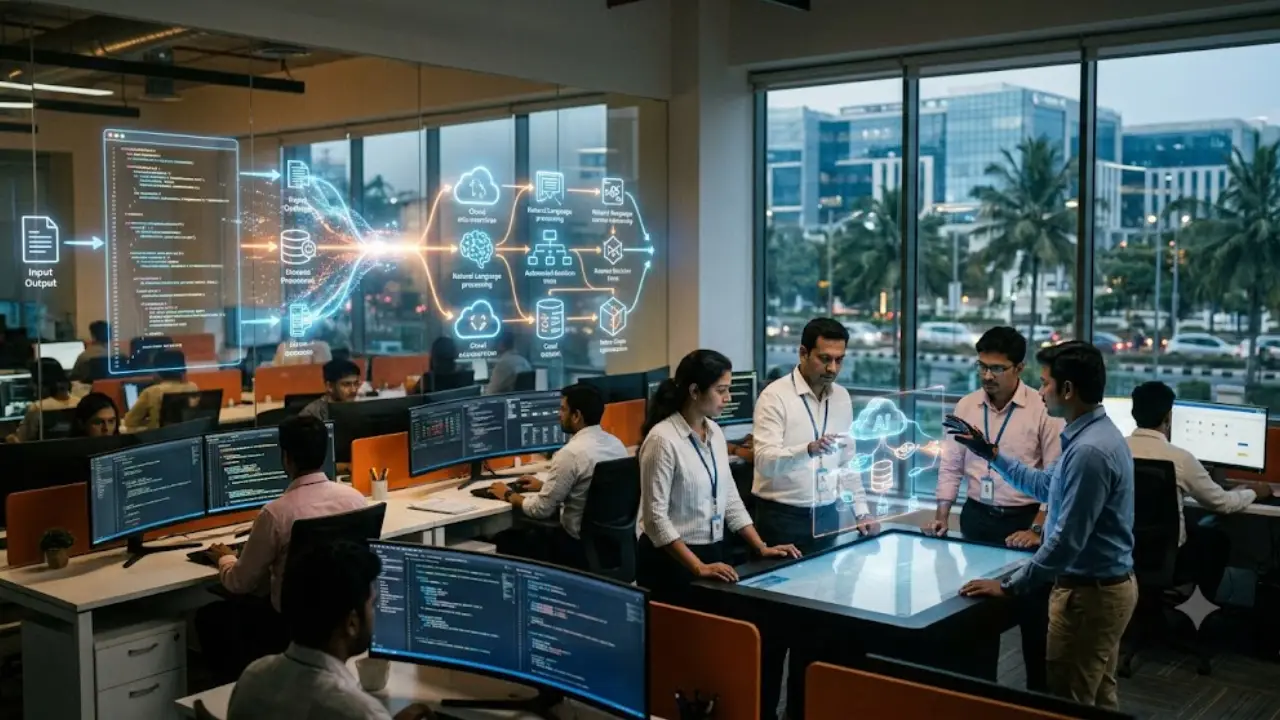
India built a global technology empire by selling human expertise at scale. AI is now asking an awkward question: what happens when the expertise gets faster?
The day the invoice becomes the story
Imagine an Indian software team receives a project.
Ten engineers are assigned.
For years, the arithmetic has been reassuringly familiar:
more work → more engineers → more hours → more revenue.
Now give those engineers powerful AI coding agents.
The ten-person team completes in three months what previously required six.
The client is delighted.
The software works.
The deadline has been beaten.
Nobody has necessarily lost a job.
And yet, somewhere in the finance department, someone is staring at the invoice.
“Why are we paying for all those hours?”
That is the question hiding underneath India’s current IT slowdown.
Reuters reported on October 1, 2026 that India’s roughly $315-billion technology sector, employing nearly 6 million people, is facing another weak earnings quarter as cautious client spending collides with AI-driven pricing pressure. Analysts surveyed by five brokerages expected only 0.7% to 3.5% sequential revenue growth for the country’s six largest IT firms in the July–September quarter.
The Nifty IT index had fallen about 27% during 2026 by the time of the Reuters report, compared with a roughly 13.4% fall in the Nifty 50.
But the most interesting number is not the stock-market decline.
It is the phrase Reuters used to describe the problem:
AI-led deflation.
Because India’s IT industry may be discovering a peculiar law of the AI economy:
If a machine makes the work cheaper to produce, the customer eventually wants some of that saving.
And that creates a problem for an industry historically built around selling human time.
India did not merely sell software. It sold time.
The genius of India’s traditional IT model was not mysterious.
A company in New York, London or Frankfurt needed software work.
Hiring locally was expensive.
India had millions of technically trained workers who could perform much of that work at lower delivery costs.
So the work moved.
The model became enormous.
A client needed 500 engineers.
An Indian IT company supplied them.
The client needed another project.
More engineers.
More hours.
More revenue.
The basic industrial machine looked something like this:
Global demand → Indian talent → billable hours → revenue → hiring → greater capacity → more contracts.
NASSCOM estimated that India’s technology industry had 5.8 million employees and $283 billion in revenue in FY25, including hardware, with exports of about $224 billion. For FY26, NASSCOM projected industry revenue of approximately $315 billion, up 6.1%, and employment of about 5.95 million.
That is not simply a successful business sector.
It is one of India’s great employment machines.
And therein lies the vulnerability.
The industry’s economic unit was often not merely software.
It was human capacity.
Then AI attacked the unit of measurement
The first mistake is to imagine AI as a machine that walks into an office and fires programmers.
That is too crude.
AI can cause disruption without eliminating an entire occupation.
It only has to eliminate some of the tasks.
Consider what happens when AI assists with:
routine coding;
code conversion;
debugging;
test generation;
documentation;
data analysis;
software maintenance;
technical research;
customer-support workflows;
repetitive business-process tasks.
The engineer remains.
The job title remains.
The office remains.
But the amount of human effort required per project falls.
That changes the economics.
And suddenly a very old question becomes relevant:
What exactly is the customer buying?
A certain number of human hours?
Or a working outcome?
That distinction could reshape India’s IT industry.
The billable-hour paradox
Suppose a task traditionally requires 10 engineer-hours.
AI reduces it to 4 hours.
If the client pays for the hours, the supplier has a problem.
If the client pays for the completed outcome, the supplier has an opportunity.
That is why the transition toward outcome-based pricing matters so much.
Reuters reported in August 2026 that major outsourcing companies including TCS, Infosys, Wipro, HCLTech and Cognizant were increasingly shifting contracts toward performance outcomes rather than hours worked, while clients demanded lower prices and greater productivity.
TCS CEO K. Krithivasan told Reuters that around 80% of contracts in its finance, human-resources and other business-services segment were based on outcome-performance measures. Reuters also reported that Persistent Systems’ clients were demanding the same work for 25%–30% less while expecting faster delivery and higher productivity.
That is not a small contractual adjustment.
It is a change in what the industry is selling.
The old proposition was:
“Pay us for the people and time.”
The emerging proposition is:
“Pay us for what the technology accomplishes.”
The difference between those two sentences could be worth billions.
AI productivity creates a strange problem
Normally, productivity is good news.
If a factory produces twice as many cars with the same workers, the owner celebrates.
But software services are unusual because the labour itself has traditionally been part of the product.
Imagine a restaurant that charged you according to the number of minutes its chef spent preparing your meal.
Now give the chef a machine that cuts preparation time by 70%.
The customer may not say:
“Wonderful. Please charge me for the seven hours the chef no longer needed.”
The customer may say:
“Wonderful. Can I have the cheaper bill?”
That is essentially the AI pricing problem.
And competition makes it harder to resist.
If one IT company can deliver the same outcome with 40% fewer labour hours, another supplier cannot indefinitely charge as if nothing changed.
Eventually somebody discounts.
Then everybody discounts.
The productivity gain becomes a pricing battle.
This is AI-led deflation.
But there is another possibility
There is a second path.
AI makes software dramatically cheaper.
That does not necessarily mean the market becomes smaller.
It could become much larger.
Think about something that once cost $1 million.
If AI reduces the cost to $200,000, companies that previously considered the project impossible may suddenly say:
“Why not?”
AI could therefore create entirely new demand.
More experiments.
More software.
More automation.
More digital products.
More cybersecurity.
More data systems.
More customised applications.
More AI integration.
More companies using technology that previously could not justify the expense.
This produces two competing economic forces:
| AI effect | Possible consequence |
| Fewer hours per project | Lower labour demand |
| Lower cost per project | Lower prices |
| Faster delivery | More projects possible |
| Cheaper software | New customers enter the market |
| Higher productivity | Higher output per worker |
| Automated routine work | Pressure on junior roles |
| New AI services | New categories of employment |
The important question is therefore not:
“Will AI reduce labour?”
It almost certainly will for some tasks.
The harder question is:
Will the new demand created by cheaper technology grow faster than the labour demand destroyed by higher productivity?
Nobody knows yet.
And that uncertainty is precisely why the Indian IT story is so interesting.
The numbers reveal a subtle break
There is another clue hiding in the industry’s statistics.
For decades, the relationship between headcount and revenue was relatively intuitive.
If revenue expanded substantially, companies generally needed more people.
Now that relationship is weakening.
NASSCOM’s FY26 estimate put technology-industry revenue growth at 6.1%, while employment growth was only around 2.3%, reaching approximately 5.95 million.
That does not prove AI caused the gap.
Several forces are involved: automation, utilisation, acquisitions, global capability centres, pricing, productivity and changes in the mix of services.
But it is exactly the kind of divergence worth watching.
If revenue can rise without equivalent workforce growth, the industry’s old equation
more people = more growth
—is becoming less reliable.
NASSCOM itself has described this period as one of non-linear growth, while its industry analysis has highlighted AI-led delivery and skills transformation.
That may be the beginning of a profound structural change.
The junior engineer has a particularly awkward problem
Here the story becomes personal.
Imagine a fresh graduate entering an IT company.
Traditionally, the graduate starts with relatively simple work.
Fix small bugs.
Write basic code.
Prepare documentation.
Test applications.
Maintain existing systems.
It is not glamorous.
But it teaches.
After two or three years, the junior engineer knows more.
Then comes a larger project.
Then architecture.
Then leadership.
The boring work was the training ground.
AI is now becoming very good at some of that boring work.
That creates a paradox.
What happens when the machine becomes better at doing the tasks humans traditionally performed to learn how to become better humans?
A recent 2026 quasi-experimental study of developers using an AI coding system found that code output increased by more than 50%, while task-based measures showed a 22% increase in completed tasks. The gains were statistically significant mainly among junior or entry-level programmers, while effects among senior developers were more limited.
That finding is particularly important for India.
If AI disproportionately accelerates junior work, the junior workforce may become economically less necessary.
But if companies hire fewer juniors, they may eventually have fewer experienced engineers.
The industry could accidentally weaken its own future talent pipeline.
The productivity paradox nobody puts on the recruitment poster
There is another complication.
More output does not necessarily mean more useful output.
AI can generate code quickly.
But someone must determine:
Is it correct?
Is it secure?
Is it maintainable?
Does it satisfy the actual business requirement?
Does it introduce hidden dependencies?
Will another engineer understand it two years later?
A 2026 meta-analysis covering 23 studies and 27 effect sizes found a statistically significant but moderate positive effect of GenAI coding assistance on productivity, with substantial variation across settings. The analysis also found no statistically significant effect on learning outcomes.
That last point matters.
Using AI to produce something faster is not the same thing as learning how to produce it yourself.
And that distinction could become crucial for the next generation of Indian engineers.
AI may create a new hierarchy of human value
The programmer of the future may not be paid primarily for typing code.
The premium could move upward.
Toward:
problem definition
What exactly needs solving?
architecture
How should the system work?
verification
Is the machine’s answer actually correct?
security
Can the system be trusted?
domain expertise
Does the solution understand banking, medicine, insurance, manufacturing or law?
judgement
Which of several technically possible solutions should actually be used?
client understanding
What does the customer really mean when the requirement is badly written?
These are difficult to automate because they involve context, accountability and consequences.
The paradox is delicious:
AI may make coding cheaper while making good judgement more expensive.
India is not simply facing an AI problem. It is facing a scale problem.
The country’s biggest advantage was scale.
Millions of workers.
Thousands of engineers available for large projects.
Mature delivery centres.
Global clients.
Well-developed outsourcing processes.
AI changes the economics of scale.
A smaller company equipped with powerful AI can potentially deliver work that previously required a much larger workforce.
Reuters reported in August that mid-sized Indian IT firms such as Persistent Systems and Coforge were gaining momentum, while traditional giants faced a more difficult environment. Reuters also noted that clients were increasingly willing to consider smaller suppliers as AI reduced the advantage associated with sheer employee scale.
This is a subtle but important shift.
For thirty years, size was an advantage.
In the AI era, speed may be an advantage.
And flexibility.
And domain expertise.
And proprietary intellectual property.
And the ability to assemble human and machine workers into a small, highly productive team.
The giant may still win.
But being giant is no longer enough.
The new IT company may look strangely smaller
Imagine two companies.
Company A
20,000 engineers.
Thousands of conventional projects.
Large hierarchy.
Revenue largely linked to people and contracts.
Company B
5,000 engineers.
AI agents embedded across development.
Highly specialised teams.
Reusable software platforms.
Outcome-based contracts.
More revenue per employee.
The old industry would naturally regard Company A as more powerful.
The new industry may not.
That is why revenue per employee could become a more revealing metric than headcount.
The question changes from:
“How many people does this company employ?”
to:
“How much economic output can this organisation produce per human?”
That is a very different industrial philosophy.
And then there are India’s GCCs
There is another pressure that deserves more attention.
Global Capability Centres technology and business units established in India by multinational companies have been expanding the country’s role beyond conventional outsourcing.
NASSCOM’s 2025 review identified GCCs as one of the major growth hotspots and reported more than 1,750 GCCs in India.
This matters because GCCs can change the labour relationship.
A multinational may increasingly decide:
Why outsource this capability at a per-hour price?
Why not build an internal AI-enabled team in India?
That does not necessarily remove work from India.
It can actually bring more high-value work into India.
But it changes who employs the engineer and who captures the margin.
The old question was:
How much work can India deliver for global companies?
The new question may be:
How much of the high-value technology itself will India-based teams own, design and operate?
That is a much more consequential question.
The great bargaining battle: who gets the productivity gain?
Suppose AI makes an engineer 30% more productive.
Who gets the 30%?
There are at least five candidates.
The client
Through lower prices.
The IT company
Through higher margins.
The employee
Through higher wages or reduced workload.
The shareholder
Through higher profits and dividends.
The consumer
Through cheaper digital services.
There is no technological rule determining the answer.
Economics does.
Competition does.
Labour bargaining power does.
Contracts do.
And scarcity does.
If AI skills become scarce, skilled workers may capture more of the gain.
If AI becomes commoditised, clients may capture more.
If suppliers develop proprietary AI systems, companies may retain more.
This is why the AI debate should not be reduced to employment statistics.
It is also a distribution-of-productivity story.
The uncomfortable possibility: fewer jobs, but more technology
This is where responsible analysis has to resist both extremes.
It would be premature to claim that AI will destroy India’s IT industry.
The evidence does not show that.
NASSCOM’s FY26 estimate still showed net job creation, while companies continue investing heavily in AI capabilities.
But it would be equally premature to assume that every existing job will survive unchanged.
The ILO’s global analysis found that roughly one in four workers are in occupations with some exposure to GenAI, while emphasising that transformation is more likely than complete replacement for most jobs.
That is probably the better lens for Indian IT.
The job may remain.
The task changes.
The team becomes smaller.
The worker supervises machines.
The contract changes.
The skill premium moves.
The career ladder changes.
And the economic value of one hour of human work changes.
That can be a revolution without looking like one.
What happens to the famous Indian IT career ladder?
The traditional ladder looked something like this:
Graduate → Junior Engineer → Engineer → Senior Engineer → Architect → Manager
AI could produce something different:
Graduate → AI-enabled engineer → Domain specialist → System designer → AI supervisor/architect → Strategic expert
Notice what disappears from the second ladder.
Not necessarily the junior employee.
But potentially the large volume of repetitive work traditionally assigned to juniors.
That could make early-career hiring more selective.
It could also force colleges and employers to rethink training.
Teaching students merely to write code may no longer be enough.
They may need to learn:
how to verify AI output;
how to formulate problems;
software architecture;
cybersecurity;
data reasoning;
domain knowledge;
communication;
systems thinking;
responsible AI use.
The machine may write the first draft.
The human increasingly has to understand whether the draft deserves to exist.
India has already started preparing for that transition
This is not entirely theoretical.
The Indian government and industry have been investing in reskilling.
MeitY’s FutureSkills PRIME programme, implemented with NASSCOM, covers emerging areas including artificial intelligence, robotic process automation, big-data analytics, cloud computing, cybersecurity, IoT and blockchain. The ministry’s 2025–26 annual report says the programme is intended to reskill and upskill IT manpower for emerging technologies.
MeitY’s Information Security Education and Awareness Phase III also targets 2.75 lakh human resources in information security over five years, including 45,000 skilled and certified cybersecurity professionals and training for 2.3 lakh students, researchers and faculty.
The challenge is scale.
Teaching millions of workers to use a new tool is one problem.
Redesigning an entire career ladder around that tool is another.
Two futures are quietly competing
Future A: AI becomes a discount machine
Companies use AI to perform existing services with fewer workers.
Clients demand lower prices.
Contracts become shorter.
Billable hours decline.
Entry-level hiring weakens.
Margins remain under pressure.
Productivity rises, but much of the benefit goes to customers.
Future B: AI becomes a demand machine
Software becomes dramatically cheaper.
More companies automate.
Entirely new categories of services appear.
Indian firms move into AI architecture, cybersecurity, data engineering and domain transformation.
Workers become more productive.
The market expands faster than labour requirements shrink.
Employment changes rather than collapses.
Both futures are economically plausible.
The evidence available today does not justify pretending we already know which one will dominate.
What we know and what we don’t
| Evidence | What it tells us | What it does not tell us |
| India’s tech sector is around $315B | The industry remains enormous | That its old business model is safe |
| Nearly 6M people work in the sector | The labour stakes are huge | That 6M jobs face identical AI risk |
| AI coding studies show productivity gains | Some software tasks can be accelerated | That total employment must fall |
| Outcome-based contracts are expanding | Pricing is changing | That hourly billing will disappear overnight |
| Junior developers can gain strongly from AI | Entry-level tasks are exposed | That junior workers will become unnecessary |
| AI can create new demand | Lower costs can expand markets | That new demand will offset every displaced task |
| GCCs continue expanding | India can capture higher-value work | That outsourcing will automatically grow |
That distinction is crucial.
Exposure is not replacement.
Productivity is not unemployment.
Revenue growth is not job growth.
And AI adoption is not the same thing as AI profitability.
The question Indian IT should really be asking
The industry has spent decades asking:
How many engineers can we deploy?
AI changes the question.
Perhaps it becomes:
How much value can one engineer, equipped with machines, create?
Then another question follows:
Who owns that value?
And finally:
How should it be priced?
Those three questions may matter more than whether an AI model can write Python in ten seconds.
Because the ultimate disruption is not the machine’s ability to produce code.
It is the machine’s ability to make human time less scarce.
And whenever something that was once scarce becomes abundant, its price tends to face pressure.
The billable hour may not disappear. But its throne is wobbling.
India’s IT industry will not wake up tomorrow and abandon hourly contracts.
Legacy agreements remain.
Complex projects still require people.
Clients still need consultants.
Regulated industries still require accountability.
AI itself creates new implementation work.
And some projects will always be difficult to price purely by outcome.
But the direction is visible.
Contracts are becoming more outcome-oriented.
AI is increasing productivity.
Clients are asking for lower costs.
Smaller firms can compete with larger ones.
Headcount and revenue are becoming less tightly connected.
Entry-level work is becoming more automatable.
And the premium is moving toward expertise, ownership and judgement.
The industry is therefore not simply automating jobs.
It is re-pricing human effort.
That may prove to be the more important revolution.
The twist is that AI may not kill the IT job. It may kill the way we count it.
For three decades, the Indian IT success story could be explained in a deceptively simple sentence:
Hire more engineers. Win more work. Bill more hours.
AI attacks the middle of that sentence.
If engineers become dramatically more productive, companies can win more work without hiring proportionately more people.
If clients demand the productivity savings, prices fall.
If prices fall, the supplier must become more efficient.
If suppliers become more efficient, fewer human hours are required.
And if fewer hours are required, the industry’s traditional relationship between employment, revenue and growth starts to loosen.
That does not automatically mean mass unemployment.
It means something more subtle—and perhaps more consequential.
The economic value of an hour is changing.
For the Indian IT industry, that could be the beginning of the real AI revolution.
Not the day a machine writes its first line of code.
Not the day a programmer loses a job.
But the day a client looks at the invoice and realises that the thing being sold is no longer really an hour.
It is an outcome.
And once the customer stops buying hours, an industry built around human time has to answer a frighteningly simple question:
What, exactly, is a human hour worth now?
The Unfoldings
India’s technology industry is approaching $315 billion in annual revenue, with employment around 5.95–6 million.
AI is not merely automating tasks; it is beginning to challenge the pricing architecture of IT services.
Outcome-based contracts are becoming more important as clients demand productivity and lower costs.
AI can create revenue deflation even while making engineers more productive.
Junior roles may be especially exposed because AI can perform some of the repetitive work traditionally used for training.
The next competitive advantage may be judgement, architecture, domain knowledge, verification and accountability, rather than raw coding capacity.
India’s enormous GCC ecosystem provides another route toward higher-value technology work.
The crucial economic uncertainty is whether AI primarily reduces the cost of existing services or creates enough new demand to expand the market.
The biggest transformation may ultimately be the separation of headcount from revenue.
The future of Indian IT may depend less on how many people it employs and more on how much valuable work each human-plus-AI team can deliver.
** Revenue and employment figures in this article refer to the broader Indian technology industry/IT sector as reported by industry sources and Reuters; they are not a single official government measurement of “IT jobs”. AI-exposure estimates describe potential task transformation, not guaranteed job losses. Company-specific productivity and contract data should not be extrapolated mechanically to the entire Indian workforce.
Frequently asked questions
Will AI eliminate India’s IT jobs?
There is currently no credible basis for claiming that AI will eliminate India’s IT workforce as a whole. Evidence points toward substantial task transformation, with particular pressure on repetitive and highly digitised work.
Why are billable hours under pressure?
Because AI can reduce the human effort required to complete some tasks. If customers continue paying primarily according to hours, increased productivity can reduce the number of billable hours required.
Does higher AI productivity automatically mean layoffs?
No. A company can use productivity gains to reduce staffing, lower prices, increase output, accept more projects or some combination of these.
Why are junior IT workers important to this story?
Entry-level employees traditionally perform many repetitive tasks while developing experience. If AI performs more of that work, companies may change how they recruit and train new graduates.
Could AI actually create more IT jobs in India?
Yes. Cheaper technology can stimulate demand for new projects and services. But the number of new jobs created relative to tasks automated remains uncertain.
What skills become more valuable?
Likely areas include system architecture, cybersecurity, domain expertise, problem definition, AI supervision, verification, client communication and decision-making.
Authentic sources and further reading
Source verification
The most important figures and claims above are supported by the latest available material:
Reuters’ 1 October 2026 report gives the current $315B scale, nearly 6M employment, 0.7–3.5% expected sequential growth and 27% Nifty IT decline.
Reuters’ August 2026 investigation supplies the crucial outcome-pricing evidence, including TCS’s reported 80% outcome-performance share in the specified business-services segment and Persistent’s reported 25–30% client price pressure.
NASSCOM reports $315B FY26 revenue, approximately 5.95M employees, 6.1% revenue growth and 2.3% employment growth.
The 2026 coding experiment found over 50% higher code output and 22% higher task completion under the studied AI system, with stronger effects among junior programmers.
The 2026 meta-analysis covering 23 studies/27 effect sizes found a moderate overall productivity effect but substantial contextual variation.
The ILO’s global study estimates 25% of employment is potentially exposed to GenAI, while distinguishing exposure from actual replacement.
MeitY’s 2025–26 report confirms India’s FutureSkills PRIME reskilling programme and its coverage of AI, cloud, cybersecurity, big data and other emerging technologies.
Related reading
AI Can Now Help Identify People in Historical Photographs — an example of a different AI transformation in which machines accelerate investigation while humans remain responsible for interpreting evidence.
Leave a Reply